
Employer-Sponsored Retirement Plans
Confluence retirement plan services help business owners and plan sponsors design, manage, and monitor their company’s retirement plan. They support the fiduciary obligations that ERISA places on sponsors while providing a benefit that can strengthen employee retention and financial well-being. At Confluence Financial Partners, we serve as a retirement plan advisor for employers across 401(k), profit-sharing, and other qualified plan structures. Our team works to bring investment oversight, vendor evaluation, and employee communication support to each engagement.
why Employer-Sponsored Retirement Plans
Your retirement plan may need more active oversight than it’s getting
As a plan sponsor, you bear real responsibility for your employees’ retirement outcomes. That responsibility extends well beyond selecting a plan provider and setting it up. The investment menu, the vendor relationship, the participant communications, and the annual plan review all require ongoing attention and documentation. Business owners often navigate this with less support than they should have.
What a well-managed employer plan can accomplish
A well-managed plan is a meaningful benefit for employees and a recruiting advantage for the business. When properly structured, it can also provide significant tax and retirement planning benefits for the business owner. Plan sponsors who are under-advised often carry real risk, from DOL audit exposure and personal liability to the reputational cost of a plan that does not serve employees well.
our approach
How we approach employer-sponsored retirement planning
We manage investments to help achieve client goals, not beat arbitrary benchmarks. Our objective based approach combines active and passive strategies, strategic planning, and tax-efficient solutions to maximize returns and minimize long-term costs.
Plan governance first
We work to help you build a documented, defensible process for every plan decision. Investment menu with intention. Fund selection is not a set-it-and-forget-it decision, so we work to review the investment lineup regularly against benchmarks and participant needs.
Vendor evaluation and accountability
We assess plan providers, record-keepers, and TPAs, working to keep costs and services aligned with participants’ interests. Participation and savings rates matter, so we work to support employee engagement through communications and enrollment programs. For business owner optimization, plan design can typically be structured to maximize the contributions available to owners and key employees.
our process
What working with our team looks like.
Plan review
We start by evaluating your current plan design, investment menu, vendor relationships, and plan documentation.
Gap analysis
We work to identify where the plan is not serving the business, the owner, or employees as well as it could.
Plan design recommendations
Our team assesses contribution structures, investment menu updates, and vendor alternatives.
meet the team
Meet our Director of Retirement Plan Services
Confluence Retirement Plan Services is led by Dave Graver, Director of Retirement Plan Services. Employer retirement planning requires both the investment analysis to evaluate plan menus and the planning depth to understand how plan design decisions affect employees and business owners alike. Dave leads Confluence’s retirement plan services engagements, bringing plan design, governance, and participant support experience to each client relationship.
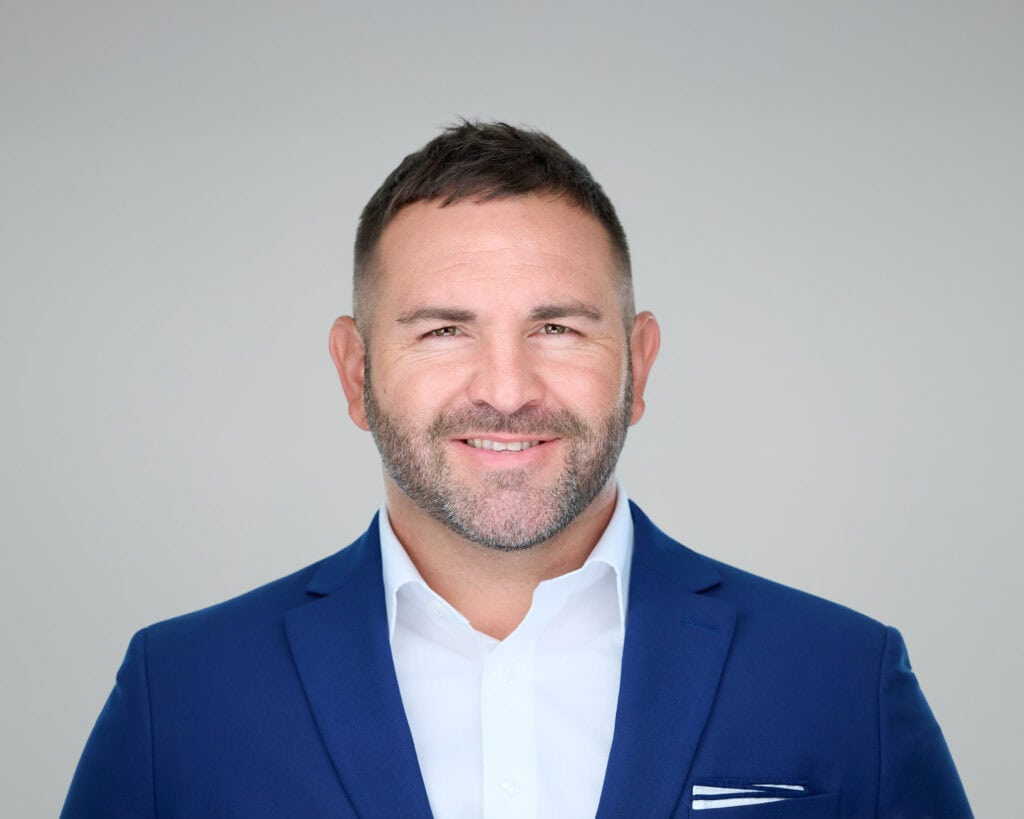
David Graver
Director of Retirement Plan Services
Is employer-sponsored retirement planning right for you?
You may benefit from working with our team on investment management if:
- You are a business owner who sponsors a retirement plan and want to be sure you are meeting your obligations under ERISA
- You are evaluating whether your current plan design is optimized for your business and your personal retirement goals
- You have not recently benchmarked your plan’s investment menu or vendor fees against the market
- You want to improve employee participation or provide better financial education within your plan
- You are considering establishing a new plan, 401(k), profit-sharing, or another qualified structure, and want guidance on plan design
Request your Consultation
Complete the form below. A member of our team will reach out within one business day to schedule your complimentary 30-minute call.
FAQ
Frequently Asked Questions
What should employers look for in a retirement plan advisor?
Employers should look for an advisor who works to evaluate the investment menu, vendor relationships, and plan fees objectively, while maintaining a focus on helping participants pursue their retirement goals. Like all Registered Investment Advisors, Confluence Financial Partners is a fiduciary, and as a fiduciary, we work to provide recommendations that we believe are in our clients' best interests based on their individual circumstances.
What are my obligations as a retirement plan sponsor under ERISA?
ERISA generally requires plan sponsors to act prudently, diversify plan investments, follow the plan document, pay only reasonable plan expenses, and avoid prohibited transactions. These obligations are ongoing, not a one-time setup decision. Plan sponsors who fail to fulfill them can face personal liability, DOL audits, and participant lawsuits.
How often should I review my company's retirement plan?
We typically recommend a quarterly investment review and an annual plan benchmarking review as a baseline. Additional reviews may be warranted after a significant market event, a change in plan participants, a vendor change, or a material shift in the business's finances. Plan documentation should be updated to reflect each review.
Can a retirement plan advisor help me optimize contributions for myself as the business owner?
Yes. Retirement plan design has a significant impact on how much a business owner can contribute tax-deferred for their own retirement. A well-structured plan, particularly one with a profit-sharing component or a safe harbor design, can often maximize the owner's contribution while maintaining compliance. We coordinate this analysis with your CPA.
What does a retirement planning fee typically include?
Retirement planning fees typically cover investment menu oversight, vendor monitoring, plan documentation support, participant communication assistance, and the plan sponsor's ongoing relationship. Fee structures vary, some advisors charge a percentage of plan assets, others a flat fee. The key is understanding what you are getting and whether the advisor is serving as a plan fiduciary.

Ready to Take the First Step?
Schedule your complimentary consultation today.