Category: Insights

Read all of the insights coming from the experts at confluence financial partners.

  • Stock Market Recap: June 2024

    • Mega-cap growth companies rallied sharply higher in June, pushing the S&P 500 higher during the month (+3.59, S&P 500 TR Index). 
    • The rally in mega-cap growth companies opened a wide gap between growth and value in June: large cap growth rose +6.74% (Russell 1000 Growth TR Index), while large cap value fell -0.94% (Russell 1000 Value TR Index).
    • Interest rates fell as data showed a drop in the rate of inflation, which pushed bond markets higher during the month (+0.95%, Barclays US Aggregate Bond TR Index)

    The outlook for corporate earnings has shifted higher- analysts now expect S&P 500 earnings to have grown +9% year-over-year the previous quarter. The increased growth expectations are driven in large part by a belief in the continued growth of investment in technology and alternative intelligence.

    This reacceleration of growth expectations has resulted in the mega-cap companies representing a large portion of the S&P 500’s value: the top 10 companies in the S&P 500 make-up 37% of the index’s value, the largest weight since the index was created. The impact of the increased concentration in the top 10 companies can be seen in the difference between the index (+15.3% YTD, S&P 500 TR Index) and the average stock (+5.1% YTD, S&P 500 Equal Weighted TR Index).

    There are high expectations for future growth in the top 10 companies of the S&P 500: their contribution to earnings over the last 12 months stands at roughly 27%, compared to a weight of 37%. This is a reminder for investors to maintain a diversified approach; markets such as US small cap stocks and international stocks offer lower valuations with an improving fundamental outlook.
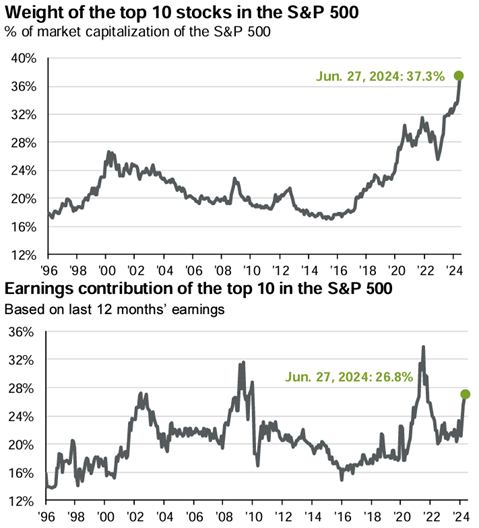
    Source: FactSet, Standard & Poor’s, J.P. Morgan Asset Management. The top 10 S&P 500 companies are based on the 10 largest index constituents at the beginning of each month. As of 5/31/2024, the top 10 companies in the index were MSFT (7.0%), AAPL (6.3%), NVDA (6.1%), AMZN (3.6%), META (2.3%), GOOGL (2.3%), GOOG (1.9%), BRK.B (1.7%), LLY (1.5%), JPM (1.3%), and AVGO (1.3%). The remaining stocks represent the rest of the 492 companies in the S&P 500.

    • Earnings season starts on July 12th; investors expect second quarter earnings to have grown +9% year/year. If earnings growth finishes that high, it would be the strongest quarterly growth rate since 2021.
    William Winkeler
    About the Author

    Bill has more than 15 years of experience in the investment industry, most recently as Managing Director of Investments at a private wealth management firm. In his role at Confluence, Bill chairs the Investment Advisory Committee and develops and implements investment strategy for clients of the firm, as well as communicates investment content with clients.

  • Stock Market Recap: May 2024

    • Markets rebounded after the first 5% drop in April, with all major stock and bond markets finishing May in positive territory.
    • Technology powered large cap growth higher (+5.99%, Russell 1000 Growth TR Index), leading all equity markets higher during the month. Small cap stocks rebounded during the month of May, with the Russell 2000 rising +5.02% (Russell 2000 TR Index). Outside the United States, developed international and emerging market equities both rose in May.
    • Major bond markets also rallied higher in May as investors’ outlook for interest rate cuts stabilized. The Barclays Aggregate Bond TR Index rose +1.70% in May.

    Equity markets are off to a strong start to 2024, despite surprising persistence of inflation and higher-for-longer interest rates.

    What has been driving markets higher through these headwinds?

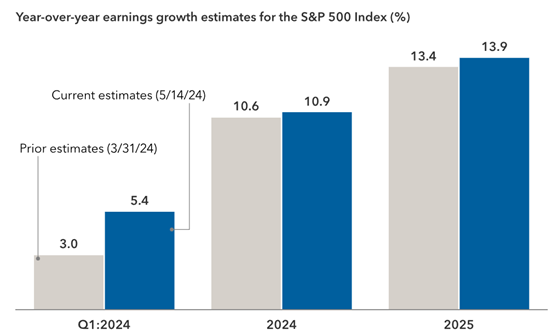
    This year has been characterized by improving fundamentals, both with corporate earnings and dividends rising above expectations. First quarter earnings for the S&P 500 have risen nearly twice the estimates from earlier in 2024, and investors have also increased 2025 earnings growth estimates to nearly +14%. Increased investments in technology, along with the supporting infrastructure, appear to have been underestimated by investors heading in 2024. Estimates for growth in 2024 and 2025 have also increased for US small cap stocks and international stocks.

    Sources: Capital Group, FactSet. Earnings growth refers to annual change in earnings per share. As of May 14, 2024.

    Dividends are also tracking ahead of expectations, thanks in part to an increase in dividend payments among technology companies. S&P Dow Jones estimates the S&P 500 dividend to increase by 6% in 2024, compared to a 5% increase in 2023. Over the long-run, stocks will follow fundamentals, and corporate earnings and dividends have been a positive surprise in 2024.

    • No rate cuts are expected, but investors will continue to focus on inflation data and Federal Reserve communication throughout the month.
    William Winkeler
    About the Author

    Bill has more than 15 years of experience in the investment industry, most recently as Managing Director of Investments at a private wealth management firm. In his role at Confluence, Bill chairs the Investment Advisory Committee and develops and implements investment strategy for clients of the firm, as well as communicates investment content with clients.

  • Stock Market Recap: April 2024

    • April saw major bond and stock markets decline due to a shifting interest rate outlook, following higher-than-expected inflation data. The S&P 500 had its first 5% or greater drop since October 2023 in April.
    • In the equity market – areas with greater sensitivity to high interest rates lagged, such as small cap stocks (-7.04%, Russell 2000 TR Index). Large cap stocks also declined, with value stocks down -4.27% (Russell 1000 Value TR Index) and growth stocks down -4.24% (Russell 1000 Growth TR Index). Emerging market equities bucked the trend and finished in positive territory (+0.45% MSCI Emerging Market NR Index).
    • As of April 30th, investors were no longer pricing a cut to the Fed Fund rate for 2024, leading major bond markets to 2024 lows (-2.53% in April, Bloomberg Barclays Aggregate Bond TR Index).

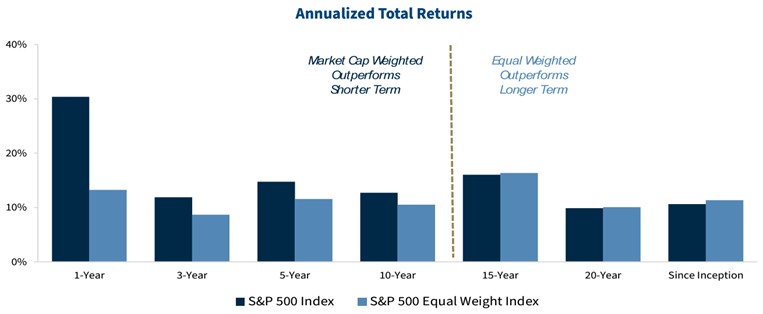
    Large growth companies continue to drive a large portion of the US equity market’s results during the past three and five years – April was no different. The S&P 500 (weighted by the size of the companies in the index) has outperformed the equal-weighted S&P 500 (representing the results of the average company) by an increasingly wide margin over the past 18 to 24 months.

    This has been driven by fast-growing technology companies: technology stocks represent roughly 30% of the market-cap weighted S&P 500, compared to 14% weight in the equal-weighted S&P 500. However, it is important to adopt a longer perspective during these unusual periods. Over the past 15- and 20-year periods, as well as since 2003 – the equal weighted S&P 500 index is ahead or in-line with the market cap weighted S&P 500. On a calendar year basis, the equal-weighted S&P 500 has finished ahead 12 out of 21 years through 2023.

    Although the market has been very top heavy, with the fast-growing technology companies driving the market, markets are cyclical, and longer-time horizons highlight the balance over time.

    Source: Raymond James, FactSet. Data as of 2/29/2024. Since inception date of the equal-weighted is 1/3/2003.
    • Inflation data will be top-of-mind given the recent hot streak in data. Federal Reserve commentary around the data will also be closely watched by investors.
    • First quarter 2024 earnings will wrap up in May. Through the end of April, earnings have finished ahead of expectations for S&P 500 companies that have reported. 
    William Winkeler
    About the Author

    Bill has more than 15 years of experience in the investment industry, most recently as Managing Director of Investments at a private wealth management firm. In his role at Confluence, Bill chairs the Investment Advisory Committee and develops and implements investment strategy for clients of the firm, as well as communicates investment content with clients.

  • Navigating Estate Taxes: 4 Mistakes to Avoid

    In the past decade, estate tax conversations have been steadily decreasing. As the lifetime credit has climbed to unprecedented highs, many wealthy Americans have come to believe that they are safely out of Uncle Sam’s reach. However, recent history is just that, it’s recent. Historically, estate taxes have been a major factor for both middle class and high-net-worth Americans. Furthermore, estate taxes are often easy targets for adjustments when fiscal gaps need closing. This article explores why estate taxes should continue to be a priority in your wealth planning, and how you can be prepared for whatever the future may hold.

    Don’t Assume Estate Taxes Won’t Be a Problem

    The current estate tax lifetime exemption is $13.61MM per individual, or $27.22MM per couple. These numbers have become so high in recent years, that many high-net-worth Americans have come to believe that they no longer need to worry about estate taxes. My advice is to be careful, because congress can change the rules at any time. As recently as 2008, the exemption was only $2MM per individual, and it was even lower than that in the 1990s and early 2000s. Even under current law if nothing else changes, the $13.61MM exclusion will be cut in half on January 1st of 2026. When tax shortfalls arise, estate taxes are often viewed as low hanging fruit for Washington. The current exclusion level is an aberration, not the historical norm.

    Don’t Let Your Estate Documents Become Stale

    The rule of thumb for most families is to have their estate plan documents reviewed every 5 years. However, if you are a high-net-worth individual with an estate tax issue, these reviews should be much more frequent. In fact, estate tax considerations should be a part of your financial plan to be reviewed and discussed at least annually and perhaps more if there is a significant change in the law. Vehicles such as irrevocable trusts and joint insurance policies can help mitigate the risk of owing estate taxes, and these vehicles and strategies should be a part of the normal cadence of planning.

    Don’t Forget to Incorporate Charitable Giving into Your Estate Plan

    Charitable giving is one of the many strategic ways to avoid estate taxes, especially if you’ve already set aside the amounts that you plan to leave to your children. Wealth that is left to charitable organizations is not subject to the 40% estate tax. This means that instead of giving $600K to your children and $400k to the government, you give $1MM to an organization you care about, or to a foundation or Donor Advised Fund that is run by your children. Most people would prefer that their heirs decide which causes receive those funds rather than a large chunk being sent to Washington.

    Make Sure You Have the Right Team:

    Your team of professionals should include not only an excellent wealth manager who can help you plan around these issues, but also an attorney and a CPA who are experts in their fields when it comes to estate taxes. These issues are complex, and they can change quickly. Make sure that you are working with professionals who have the knowledge and the bandwidth to give these issues the attention they deserve.

    Estate planning is a dynamic field that requires regular attention, especially for those with significant wealth. High-net-worth individuals should not only reassess their estate plans frequently but should also consider incorporating charitable giving as part of their strategy. Be sure your planning team includes knowledgeable wealth managers, attorneys, and CPAs as this is crucial as you navigate the ever-changing landscape of estate taxes. Complacency can be costly – proactive estate planning should remain a critical element of your financial health.

    If we can be of help to you and your family, please give us a call!

    Greg Weimer
    About the Author

    At the core of his personal and professional life, Greg is passionate about helping individuals and families maximize their lives and legacies. His dedication to this mission shines through as an individual, wealth manager, and leader.

    Confluence Financial Partners and its affiliates do not provide tax, legal or accounting advice. This material has been prepared for informational purposes only, and is not intended to provide, and should not be relied on for, tax, legal or accounting advice. You should consult your own tax, legal and accounting advisors before engaging in any transaction.

  • Your Financial Guide for a Career Transition

    Navigating a job change is a significant undertaking, especially for those with considerable assets and financial interests. This guide is designed for professionals, including executives, physicians, and business owners as they work through the intricacies of transitioning to new opportunities.

    Here are some important things to consider:

    • Review your compensation plan.

    Understanding your compensation package is important, because compensation is usually a huge part of transition decision. Beyond salary, bonuses, and deferred compensation, it’s essential to assess the long-term value of your total package. For example, if you are re-locating, consider the impact of cost-of-living adjustments.

    Don’t forget to evaluate non-monetary benefits such as professional development opportunities, wellness opportunities, and overall company culture. All of these can have a significant impact on your job satisfaction and overall well-being.

    • Evaluate your retirement plan.

    What do I do with my old retirement plan(s)?

    Roll into an IRA: Working with a financial advisor can help you determine if rolling into an Individual Retirement Account makes sense. The benefits of this option include having more investment flexibility and control. Typically, you will have a broader range of investment options compared to an employer sponsored 401(k) plan. This allows you to diversify your portfolio while also consolidating accounts if you have multiple 401(k)s with previous employers. If you work with an advisor, you will have professional investment management as well as financial planning available. A good financial advisor will also be able to help with tax and estate planning matters, though he/she cannot replace your CPA or attorney.

    or

    Move your old retirement plan to your new employer: Most employer sponsored retirement plans allow for assets from previous retirement plans to flow into the new plan. This is certainly better than leaving the assets with your old employer’s plan, but this option likely does not include the investment options and flexibility as well as professional management and planning found if you roll assets into a managed IRA. That said, it may be your lowest cost option.

    • Understand changes to your health insurance.

    Be aware if there is a waiting period for health insurance with your new employer. If that is the case, look into extending your previous employer’s coverage through COBRA if there is a gap.

    Have a solid understanding of the different health insurance plans offered by your employer and consider factors such as the network of providers, deductibles, co-pays, coverage for prescription drugs and preventative care to name a few.

    Take advantage of  tax-advantaged accounts like Flexible Spending Accounts (FSA)s and Health Savings Accounts (HSA)s if your employer offers them.  These accounts can help you save money on qualified medical expenses. Additionally, HSAs can serve as an additional retirement savings vehicle.

    • Review Stock Options and Equity Compensation Programs.

    If your previous employer offered stock options or equity, be sure to understand the vesting schedules and the implications of leaving.

    Equity compensation can significantly increase your wealth, but also add complexity to your financial and tax planning picture. For example, the decision to exercise stock options should be timed to optimize tax implications and align with your broader financial goals, risk tolerance, and time horizon. Working with a financial advisor can help you make an informed financial decision.

    Gregory Weimer
    About the Author

    Gregory developed a passion for the financial services industry early in life, drawn to the meaningful impact investing and thoughtful financial planning can have on people’s lives.

  • Stock Market Recap: March 2024

    • Stock and bond markets rallied during March, with broadening of results- large cap value stocks (+5.0%, Russell 1000 Value TR Index), small cap stocks (+3.6%, Russell 2000 TR Index), and international stocks (+3.3%, MSCI ACWI Ex-USA NR Index) finished the month ahead of large cap growth stocks (+1.8%, Russell 1000 Growth TR Index).
    • Economic data continues to look strong in the United States. The Federal Reserve also confirmed their forecast of three 0.25% interest rate cuts in 2024.

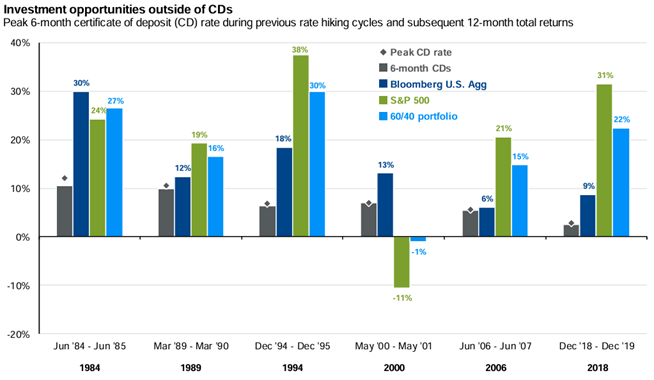
    Last month we discussed the difficulty in forecasting changes in interest rates. During March, investors spent the month aligning their outlook with the Federal Reserve’s guidance, which remains some level of interest rate cuts sometime later this year. While the exact timing cannot be known, we do know that historically there have been opportunities to shift out of cash investments near peak interest rates.

    Going back to the six previous cycles since 1984, investors have been better off investing in bonds, US stocks or a balanced portfolio compared to staying in cash during the 12-months following the peak level of interest rates. Forecasting the exact time of peak interest rates/rate cuts is fruitless, but for long-term investors there is an opportunity to look beyond cash.

    Source: Bloomberg, FactSet, Federal Reserve, Robert Shiller, J.P. Morgan Asset Management. The 60/40 portfolio is 60% invested in S&P 500 Total Return Index and 40% invested in Bloomberg U.S. Aggregate Total Return Index. The S&P 500 total return figure from the 1984 period was calculated using data from Robert Shiller. The analysis references the month in which the month-end 6-month CD rate peaked during previous rate hiking cycles. CD rate data prior to 2013 are sourced from the Federal Reserve, whereas data from 2013 to 2023 are sourced from Bloomberg. CD subsequent 12-month return calculation assumes reinvestment at the prevailing 6-month rate when the initial CD matures.

    • The Federal Reserve meets at the end of April, they are expected to hold interest rates constant. Investors will look for updates around the timing of interest rate cuts and balance sheet changes during the presentation. 
    • The inflation report and jobs report for March will be watched by investors for signs of continued progress on the inflation front, and for any weakening in the jobs market.
    William Winkeler
    About the Author

    Bill has more than 15 years of experience in the investment industry, most recently as Managing Director of Investments at a private wealth management firm. In his role at Confluence, Bill chairs the Investment Advisory Committee and develops and implements investment strategy for clients of the firm, as well as communicates investment content with clients.

  • Disability Insurance Planning for Physicians: Key Facts & Considerations

    Nearly 1 in 5 people living in the United States will suffer a disability lasting more than one year before the age of 65.1


    Imagine not being able to practice your specialized medical skills due to illness or injury. The financial impact could be devastating for you and your family. As a physician, your income hinges on your ability to work. That’s why individual disability insurance as part of your financial plan is crucial for safeguarding your earning potential.

    Choosing disability insurance involves understanding the different types and the benefits each brings. For example, there are two categories of disability policies, short-term disability and long-term disability. Short-term disability policies are typically obtained as a group policy benefit from one’s employer while long-term disability policies are also offered as a benefit through an employer BUT are more commonly purchased as an individual policy through a broker or financial advisor.

    Additionally, you can purchase own-occupation coverage or any-occupation coverage. The difference between the two is meaningful. Under an own-occupation policy, a person is typically considered disabled if they are unable to perform the material and substantial duties of the job they were working at the time they became disabled. Under an any-occupation policy, a person is considered disabled if they are not able to perform substantial duties of any job for which the person may earn a certain percentage of their pre-disability earnings.  

    For physicians, it is essential to work with an advisor who understands your needs and unique situation to recommend the right disability insurance strategy.

    Beyond basic understanding of disability insurance, it’s important to understand key factors like the carrier, benefit amount, elimination period, and renewal options.

    • Insurance Carrier – know who you are working with. Currently, only 5 carriers offer “true” own-occupation coverage.
    • Benefit Amount – the IRS publishesd “Issue & Participation” amounts based on your income and existing disability coverage.
    • Waiting Period – the amount of time one must wait to collect benefits when disabled – typically 90, 180, 365, or 730 days.
    • Benefit Period – how long one will be eligible to receive their tax-free benefit. This is typically to age 65, 67, 70, or lifetime.

    The above list is not all encompassing but should be considered as you construct your insurance package.

    At Confluence Financial Partners, we work with physicians to secure and protect their income in the event an unexpected illness or injury becomes reality. Please reach out if you would like to start the conversation today.

    Life and disability insurance and life insurance with long-term care benefits are not issued through Confluence Insurance Services. Products and services referenced are offered and sold only by appropriately appointed and licensed entities and financial advisors and professionals. Not all products and services are available in all states. 

    Rob Linkowski
    About the Author

    Rob Linkowski brings more than 35 years of experience in designing and providing quality life and disability insurance programs to his clientele of medical professionals, business owners, family and friends. Rob is passionate about advocating for his clients and not the insurance companies.

  • Maximize Your Year End Giving: Charitable Planning Strategies for Individuals

    As the end of the year approaches, it’s an opportune time for clients to utilize strategies that align charitable goals with their financial objectives. In this article, we will explore various charitable planning opportunities and strategies to leverage to help our clients optimize their giving while improving their overall financial situation.

    One of the primary incentives for charitable giving is the potential to reduce taxable income. However, timing and method play a crucial role in maximizing these benefits. Below are several techniques to consider as part of year-end planning:

    • Avoiding Capital Gains Tax: Donors avoid paying capital gains tax on the appreciation of the asset.
    • Maximized Tax Deduction: They receive a charitable deduction for the fair market value of the donated securities, provided they’ve held the asset for more than one year.
    • Watch Your Limits: The IRS places limits on the amount clients can deduct for charitable contributions. For cash donations, the limit is typically 60% of AGI, while donations of appreciated assets are limited to 30% of AGI. If the total contributions exceed these limits, the excess can be carried forward for up to five years.
    • Helps Portfolios: This strategy is particularly useful in bull markets, where many clients may have appreciated assets they would otherwise sell to rebalance their portfolios.
    • Satisfies Required Minimum Distributions (RMDs): For clients who have reached their required beginning date, QCDs can reduce taxable income by offsetting RMDs.  However you need to be careful to make QCDs first, before taking any other income yourself.  The first dollars out of a qualified account are the RMD dollars; if you take your RMD first and then try to make a QCD later, it won’t count.
    • Tax-Free Distribution: Unlike regular withdrawals, the QCD is excluded from the client’s taxable income, offering a substantial benefit for those who don’t itemize deductions, which can help clients stay within lower tax brackets or avoid Medicare premium increases.
    • This strategy is particularly advantageous for clients who may no longer need the full amount of their RMD for living expenses but are still required to take it.

    One way to implement this is through a Donor-Advised Fund (DAF):

    • Clients can make a lump-sum contribution to a DAF and receive an immediate tax deduction.
    • In subsequent years, the client can take the standard deduction and not make additional charitable contributions until the next “bunching” year.
    • The funds can be distributed to charities over several years allowing donors to maintain their philanthropic commitments.
    • It’s ideal for clients facing a windfall year or who have highly appreciated assets they wish to donate.
    • For clients seeking to create a structured giving plan, or for those who may not have specific charities in mind yet, a DAF can serve as a helpful intermediary.
    • Generate Income Streams: Charitable trusts allow donors to convert highly appreciated assets into a steady income. For example, with a Charitable Remainder Trust (CRT), donors or their beneficiaries receive a fixed or variable income for life or a specified period. This can be an attractive option for retirees or clients seeking supplemental income while also supporting charities in the future.
    • Grow the Legacy: One of the most significant benefits of charitable trusts is the potential to transfer appreciated assets, such as real estate or stocks, without triggering capital gains taxes.  When assets are placed into a Charitable Remainder Trust (CRT) and sold, the proceeds are untaxed to the trust, allowing more principal to be retained for both income generation and charitable legacies.
    • Immediate Tax Deduction: Contributions to a charitable trust are eligible for an immediate charitable deduction, based on the present value of the future charitable donation. This deduction can help offset taxable income in the year of the contribution, providing immediate tax relief.

    Your wealth manager can help you formulate a personalized year-end charitable giving plan. Here’s a checklist approach to developing it:

    1. Identify Charitable Goals: What causes are important to you?
    2. Review Taxable Income: Determine whether itemizing or taking the standard deduction makes sense.
    3. Evaluate Assets: Identify appreciated securities or other assets that could be donated.
    4. Consider Timing: Ensure donations are made before December 31 to qualify for the current tax year.
    5. Explore Donor-Advised Funds: If clients plan to give over multiple years, DAFs may be an optimal solution.
    6. Engage Family: Involve family members in the charitable conversation.
    7. Check Matching Programs: Encourage clients to explore employer matching gift
    Gregory Weimer
    About the Author

    Gregory developed a passion for the financial services industry early in life, drawn to the meaningful impact investing and thoughtful financial planning can have on people’s lives.

  • Stock Market Recap: September 2023

    Month in Review

    • Stocks had their worst month since December 2022 and bonds fell for the fourth straight month. 
    • Rising Treasury yields were the primary catalyst – the 10-year Treasury yield hit a 16-year high during September.
    • Restrengthening inflation data and the prospect of additional interest rate hikes by the Federal Reserve are the main catalysts for the pressures.

    Bond Yields Return to Average

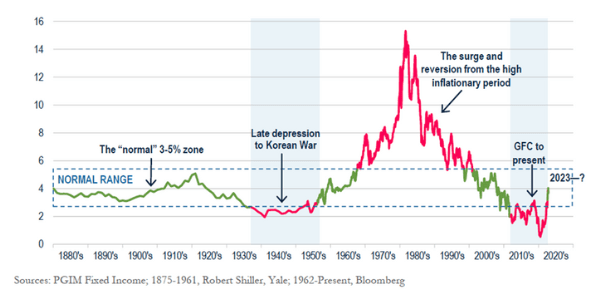
    Despite nearly a decade of low interest rates, the 10-year Treasury yield typically averages 3% to 5% yield, going back to the late 1800’s. For the first time since 2007, the 10-year Treasury rose to 4.5%, comfortably returning to long-term averages. Recent inflation data was stronger than expected, contributing to the increase in yield, along with the prospect of additional rate hikes from the Federal Reserve. The increase in yields reduces the value of bond investments in the short-term, and higher yields present a more attractive alternative to stocks – two reasons stocks and bonds struggled in August and September.

    What’s on Deck for October?

    • Outside of fundamentals, there are headwinds from the on-going autoworkers’ strike, and a potential shutdown of the US government. Both events historically have not had lasting impacts on the economy and markets.
    • The surprisingly strong labor market was the primary reason the predicted 2023 recession did not happen – investors will be watching job creation and unemployment claims data closely for any softening.
    • An additional interest rate hike in November or December is very much up in the air. Inflation data had strengthened somewhat, along with energy prices increasing sharply since June. It is unclear if this is enough for the Federal Reserve to hike one more time.

    Download the September 2023 Market Recap below:

    William Winkeler
    About the Author

    Bill has more than 15 years of experience in the investment industry, most recently as Managing Director of Investments at a private wealth management firm. In his role at Confluence, Bill chairs the Investment Advisory Committee and develops and implements investment strategy for clients of the firm, as well as communicates investment content with clients.

    [wpcode id=”4200″]

  • Stock Market Recap: August 2024

    • Broad-based gains during the month of August, with US large cap stocks finishing the month up +2.43% (S&P 500 TR Index). In the US, large cap value (+2.68%, Russell 1000 Value TR Index) finished ahead of large cap growth (2.08%, Russell 1000 Growth TR Index) for the second consecutive month.
    • US small cap stocks took a breather after a strong July, finishing August down -1.49% (Russell 2000 TR Index). Outside the US, developed international equities benefitted from a weakening US dollar, rising +3.25% in August (MSCI EAFE NR USD).
    • Bond markets rose for the fourth straight month in August, with the Barclays US Agg Bond TR Index finishing the month +1.44%.

    The Federal Reserve is poised to cut interest rates in September, the first interest rate cut since they began increasing interest rates in March 2022. Investors are now pondering, “what happens next?”: a “soft” or “hard” landing for the economy.

    While not officially defined, a soft landing would be a continued decline in inflation and interest rates, without growth slowing down enough to enter a recession. Hard landing would be the opposite – a continued increase in unemployment and a slowdown in economic growth, resulting in a recession. Soft landings are historically less common, with the most recent (and classic case) being the 1994-1995 period.

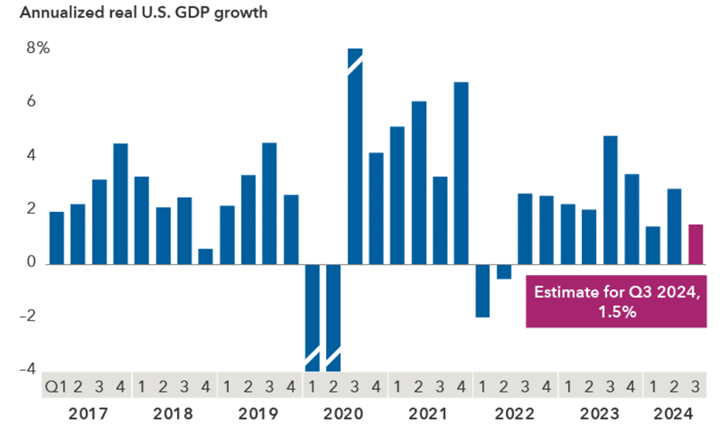
    Inflation has fallen closer to the Federal Reserve’s target rate, while unemployment has also begun to increase, prompting the likely rate cut in September. However, other signs indicate continued strength in the economy: for example, estimates for GDP growth this quarter stand at +1.5%. With no clear forecasts for a soft or hard landing, investors have priced in three to four rate cuts by the end of 2024, indicating expectations that the Federal Reserve will start and continue rate cuts in September.

    Sources: Capital Group, Bureau of Economic Analysis, FactSet. Figures for Q1:20, Q2:20, and Q3:20 are –5.5%, –31.6%, and 31.0% respectively, and are cut off by the y-axis given the extreme fluctuations associated with the COVID-19 pandemic. Estimate for Q3:24 is based on the mean consensus estimate from FactSet. As of August 22, 2024.

    • With  earnings season wrapped up in August, investors will be watching the Federal Reserve’s FOMC meeting closely for color around a potential rate cut. 
    William Winkeler
    About the Author

    Bill has more than 15 years of experience in the investment industry, most recently as Managing Director of Investments at a private wealth management firm. In his role at Confluence, Bill chairs the Investment Advisory Committee and develops and implements investment strategy for clients of the firm, as well as communicates investment content with clients.