Category: Insights

Read all of the insights coming from the experts at confluence financial partners.

  • Banking Safety in Uncertain Times: A Guide to Deposit Accounts and Cash Investments

    The banking system recently became front-page news following the failure of two banks in March. The headlines related to bank failures can illicit very emotional responses about safety of deposit accounts and cash investment solutions.

    We believe it is more important than ever to look through the headlines to the fundamentals of cash management.

    Cash management fundamentally breaks down into two categories:

    1. Deposit accounts, and
    2. Cash investment solutions.

    While the two have similarities, there are fundamental differences with structure and protection.

    Deposit Accounts

    • Bank Deposits: Interest-bearing account at a banking institution, such as a savings or checking account.
      • These accounts do not have market risk.
      • Insured by the Federal Deposit Insurance Corporation (FDIC) to applicable limits
        • FDIC deposit insurance is backed by the full faith and credit of the United States government. Currently, FDIC coverage extends to $250,000 per owner (and per account type), considering the underlying banking institution. For example, a joint account may have $500,000 of FDIC coverage at a single banking institution.

    Cash Investment Solutions    

    • Certificates of Deposit (CDs):  Investment that earns interest on a lump sum basis for a defined period of time.
      • In contrast to deposits, CD’s typically offer higher interest rates versus bank deposits to compensate for monies being unavailable during the life of the investment.
      • FDIC coverage applies to $250,000 per individual per issuing institution.
    • Individual Treasuries: Securities issued by the US Government, can be interest-bearing or zero coupon (earn lump-sum at maturity). The term of Treasuries can vary significantly: 4 weeks to 30 years.
      • Exempt from state and local taxes, but subject to federal tax.
      • Not covered by FDIC insurance, rather explicitly backed by the full faith and credit of the United States government.
    • Government Money Market Mutual Funds: Mutual funds that invest in Treasuries and US Government securities, paying interest on a recurring basis. Government money markets target a stable $1.00 value (not guaranteed)
      • Not FDIC insured.
      • Money market mutual funds underwent significant changes starting in 2016, which introduced redemption fees and liquidity gates, an effort to introduce a tool to combat any “run” on money markets. Only government money market funds are exempt from the rules surrounding redemption fees and gates (however, they can adopt them if previously disclosed to investors). Currently, none of the government money market funds offered by Raymond James have adopted redemption fees and gates.

    In addition to FDIC insurance and backing of the full faith and credit of the US government, most assets held at firms such as Raymond James are covered by the Securities Investor Protection Corporation (SIPC), to applicable limits. The SIPC was established in 1970 and protects client assets up to $500,000, including $250,000 of cash. SIPC account protection would apply in the event a firm fails financially and is unable to meet obligations to clients, not against a loss in market value.

    Despite the negative and unsettling headlines, there are multiple robust cash management solutions available to clients, with multiple layers of risk mitigation. At Confluence Financial Partners, we believe in the soundness of our banking system and maintain complete confidence in our client cash management tools. 
    William Winkeler
    About the Author

    Bill has more than 15 years of experience in the investment industry, most recently as Managing Director of Investments at a private wealth management firm. In his role at Confluence, Bill chairs the Investment Advisory Committee and develops and implements investment strategy for clients of the firm, as well as communicates investment content with clients.

  • Finding Balance: Living in the Now, Learning from the Past, and Planning for the Future

    Are you focused on the past, present, or future?

    What is your time ratio? Here are a few thoughts to consider:

    10% – Past
    We benefit greatly from history, experiences, and lessons from our past. Unfortunately/fortunately, the past is over. We can no longer control or change it. Hold on to the positive experiences and valuable lessons, and leave the regrets behind.

    60% – Present
    It’s really all we have! Living in the moment is a gift. Waking up to the now and having a “be where your feet are” attitude is an important perspective to keep as you focus on the present. Let’s be careful not to allow fear, or distractions like cell phones, to steal our moments.

    30% – Future
    Happiness comes from believing your best days are ahead. Planning reduces stress, creates energy and increases the likelihood of a bright future. Don’t wonder if your best days are ahead of you, take concrete steps so that you can be sure!

    Let’s encourage each other to learn from the past, live in the present and believe in the future.

    We are grateful to be a part of your journey!

    Greg Weimer
    About the Author

    At the core of his personal and professional life, Greg is passionate about helping individuals and families maximize their lives and legacies. His dedication to this mission shines through as an individual, wealth manager, and leader.

  • Is Your Family Financially Prepared for the Unexpected?

    If you were gone tomorrow, would your family be financially OK?

    That is a jarring question, and one that most of us try to avoid.

    As difficult as this scenario is to consider, however, we owe it to ourselves and our loved ones to be able to answer the question with certainty.

    Below are some points to consider:

    • Estate Plan
      • Do you have up to date wills, trusts, and other applicable documents? Have you gone through the documents in the past 5 years? What has changed since they were written? Is it time for an update?
      • Does your estate plan help and encourage family collaboration while safeguarding relationships? Many a family has been torn apart by disputes regarding an inheritance.
    • Life Insurance
      • Do you have life insurance in place? Is it enough so that your spouse and children would not have to worry about money when you are gone?
      • We can’t control very much in this situation, but we can control the windfall that our dependents would receive if we die unexpectedly.
    • Communication
      • Do your loved ones know the structure of your estate plan? Do they know what your expectations are for the money? If you have young children, this may be a conversation to have with your spouse and the person who would be the legal guardian for your children. If you have adult children, this could be a family meeting where the plan is fleshed out in more detail.
      • Studies show that aging parents have a difficult time bringing up finances with their children. This is understandable, but it needs to happen at some point. Your adult children can handle it, and the risks of them knowing how much money the family has pale in comparison to the burden that an unexpected inheritance can be.
    • The Things No One Thinks About
      • Passwords, document locations, lock boxes, safe combinations, utilities, iPhone lock codes, and anything else that your loved ones would need.
      • If you knew you weren’t going to wake up tomorrow, what information would your loved ones need to handle everything? Consider a tool like everplans to help with this.
    • Trusted Person
      • Is there someone in your life whom trust to be there for your family if something happens to you? We work with many clients who view us as that person who they trust to be across the table from their spouse should this situation arise. We are often one of the first calls that is made, because we know where everything is and we’ve helped clients through this before.

    So, we ask again.

    If you were gone tomorrow, would your family be financially ok?

    If you aren’t sure, take time to reflect. We at Confluence Financial Partners have been helping clients answer that question in the affirmative for decades, and we would be honored to be able to help you as well. We know this isn’t a pleasant thing to work through, but it’s worth it, and you owe it to those you love.

    Greg Weimer
    About the Author

    At the core of his personal and professional life, Greg is passionate about helping individuals and families maximize their lives and legacies. His dedication to this mission shines through as an individual, wealth manager, and leader.

  • Should Millennials Plan on Social Security?

    Social Security, started in the 1930s as a part of FDR’s New Deal, has been under fire since I can remember. All the while, the program has been helping fund the retirement of some 47 million Americans, with another 19 million on survivor or disability benefits. What started out as a way to ensure elderly Americans had some form of income has turned into a major piece of the US economy.

    As we help our younger clients plan for retirement, we often hear, “Let’s not plan on Social Security, I don’t think it will be there by the time I retire.” While we understand where this attitude is coming from, we don’t think it reflects reality.

    Here’s why:

    • Social Security is funded by a separate payroll tax (FICA) that comes out of paychecks up until an individual reaches $160,200 in earned income (2023). That means, that for the first $160,200 each earner makes, 6.2% goes to Social Security, with another 6.2% coming from the employer.
    • That’s a total of $19,864 that goes to Social Security for someone who earns $160,200.
    • These amounts are then paid out directly to retirees, survivors, and disabled individuals.

    As long as there are people working in the United States, there will be money going into, and then out of Social Security.

    “But what about the trust fund?”

    • As discussed above, Social Security is funded directly from payroll taxes. Up until very recently, the ratio of working to non-working Americans had been high enough that Social Security benefits were fully funded each year.
    • However, as Baby Boomers retire and birthrates continue to decline, this is changing. If payroll taxes are not enough to current obligations, the difference is paid by the asset reserves in the Social Security trust fund. As more and more workers retire, the trust fund is expected to be depleted.

    By the most recent estimates, the trust fund assets will be spent down by 2034. At that point, Social Security would officially be insolvent.

    “That’s what I mean! Once Social Security is insolvent, I won’t get any benefits!”

    But what does insolvency actually mean?

    • Assuming no legislation is passed to shore up the program, all benefits will be cut to about 79% of what they are today.
    • 79% is not 0%. Far from it, in fact, 79% is still solid amount of guaranteed income that the younger generation can plan on as a piece of their overall retirement picture.

    “That’s it? That doesn’t sound as bad as what I’ve read in the news.”

    No, it doesn’t. For younger workers who have plenty of time to factor such a possibility in their long-term planning, the potential reduction would not be life changing. A relatively modest increase to retirement savings would make up for the potential shortfall.

    In reality, Congress will be forced to act, there will likely be changes to Social Security at some point. These changes will probably make sure that current benefits are not cut, and that Americans with no time to adjust will not have the rug pulled out from under them. For younger Americans, the fact remains that as long as we have workers and payroll taxes, Social Security will be there in one way or another.


    Disclaimer: This analysis could certainly change pending action by Congress. We are in no way trying to predict the future, but we believe this analysis is reasonable based on the current landscape.

    Gregory Weimer
    About the Author

    Gregory developed a passion for the financial services industry early in life, drawn to the meaningful impact investing and thoughtful financial planning can have on people’s lives.

  • Stock Market Recap: February 2024

    Month in Review

    • Rally continued for stocks in February, with the key development of broader participation- for example, US small cap stocks had a strong month.
    • String of inflation data and commentary from the Federal Reserve pushed bond yields higher during February.
    • The inflation report released during the month (January CPI) showed prices rising more than expected, driven by higher housing related costs.

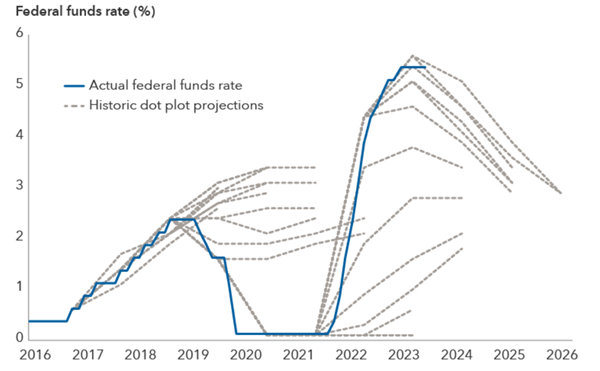
    Investors are curious as to when the Federal Reserve will start lowering interest rates. During February, investors recalibrated expectations once again for the start of rate cuts, believing that the first reduction will be pushed back to June 2024. This change makes sense for various reasons: inflation continues to remain somewhat firm, and the labor market remains very strong.

    Historically, forecasting the path of interest rates has been notoriously difficult to do and ultimately, introduces unwarranted noise into investors’ outlooks. The chart below shows how even the Federal Reserve struggles to predict its own interest rate decisions.

    Source: Capital Group, Bloomberg. As of February 23, 2024. Federal funds rate data from January 2016 to February 2024. Forward looking dot plot projections are reported quarterly from September 2016 through December 2023.

    • Inflation data will be in focus as investors watch for any signs of continued increases of prices. The February CPI report is released on March 12th and expected to show declining inflation.
    • The Federal Reserve’s March meeting (FOMC) will be closely watched for commentary around the outlook for growth and inflation. Fed Chair Jerome Powell has already indicated a March rate hike is off the table.
    • As of February 29th, 97% of the S&P 500 companies had reported earnings, with the remainder wrapping up in March. With 97% of companies reporting, year-over-year earnings growth came in at +4%. 
    William Winkeler
    About the Author

    Bill has more than 15 years of experience in the investment industry, most recently as Managing Director of Investments at a private wealth management firm. In his role at Confluence, Bill chairs the Investment Advisory Committee and develops and implements investment strategy for clients of the firm, as well as communicates investment content with clients.

  • Multi-Generational Legacies: Communicating Your Estate Plan

    $96 Trillion is going to pass from one generation to the next over the coming 30 years.

    This is either going to go smoothly or poorly, and much of that answer will come down to estate planning.

    Your estate plan is a crucial aspect of securing your family’s future, and communicating this wealth plan effectively to your children is perhaps even more important.

    1. Talk About It

    This might seem basic, but start the conversation early. Don’t wait for a crisis to discuss your estate plan. Start the conversation with your children while everyone is in good health and spirits. Choose a suitable time and place for the discussion, ensuring minimal distractions. This will allow your children to focus on the important matters at hand without feeling rushed or pressured.

    • Clarify Roles and Responsibilities

    Clearly communicate who will be responsible for executing your wishes and managing your affairs if you are unable to do so. If your adult children will be filling these roles, tell them. Don’t assume that your oldest child will understand why you made your middle child the executor. Explain your decisions and choices so that when the time comes there won’t be any confusion or hurt feelings.  

    • Educate Your Heirs on the Structure of Your Estate Plan

    You don’t have to share all of the details right away, but make a plan for bringing in the next generation into your financial picture. These discussions are difficult to begin in most households, but at some point you should consider letting your adult children know what you have and how all of it will be transferred. Eventually you should share detailed information about your assets, including properties, investments, and savings. Do you have a financial plan with your financial advisor? It would be wise to share it with your children.

    When in doubt, over communicate. You would be amazed at the disagreements that will come up after you are gone, many of which are due to a lack of direction and clarity on your part. Don’t assume your children will know what to do. Spell it out for them.

    • Address Potential Concerns and Questions

    You don’t have to share all of the details right away, but make a plan for bringing in the next generation into your financial picture. These discussions are difficult to begin in most households, but at some point you should consider letting your adult children know what you have and how all of it will be transferred. Eventually you should share detailed information about your assets, including properties, investments, and savings. Do you have a financial plan with your financial advisor? It would be wise to share it with your children.

    When in doubt, over communicate. You would be amazed at the disagreements that will come up after you are gone, many of which are due to a lack of direction and clarity on your part. Don’t assume your children will know what to do. Spell it out for them.

    Greg Weimer
    About the Author

    At the core of his personal and professional life, Greg is passionate about helping individuals and families maximize their lives and legacies. His dedication to this mission shines through as an individual, wealth manager, and leader.

  • Stock Market Recap: September 2024

    • Stock and bond markets continued to rally in September, following the Federal Reserve’s first interest rate cut.
    • Gains expanded beyond market leaders, such as large cap growth and technology stocks, with broader participation within the S&P 500, large cap value, small cap stocks, and international stocks.
    • The S&P 500 Index total return of +22.08% year-to-date as of September 30th represents its best start to a year since 1997, and the best start to a Presidential election year in its history.

    The Federal Reserve reduced the Federal Funds Rate by 0.50% as expected in September, ending the rate hiking cycle that began in March 2022 and featured over 5% worth of interest rate increases. 

    The market’s outlook largely shifted in early July, when the June inflation report affirmed the outlook for declining inflation, clearing the way for the September rate cut. Since that period, stock and bond market leadership has shifted as the economic and fundamental outlook has changed.

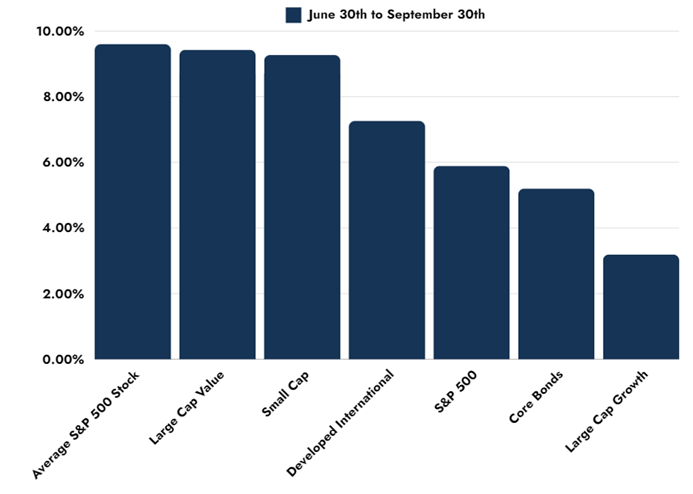
    Since June 30th (after the inflation report and rate cut), market leadership has broadened beyond the Magnificent 7 stocks. The Equal-Weighted S&P 500 Index rose +9.60%, ahead of the market-cap weighted S&P 500 TR Index (+5.89%). Within large cap stocks, large cap value gained +9.43%, ahead of large cap growth’s +3.19% gain. Small cap stocks also participated in broadening, with the Russell 2000 TR Index rising +9.27% during the third quarter. Lastly, core bonds (Barclays US Agg Bond TR Index) rose +5.20%, pulling ahead of money market funds in 2024 as short-term rates begin to decline. The changing environment highlights how dynamic financial markets can be and serves as a reminder of the importance of maintaining a diversified approach to investing.

    Sources: Morningstar, June 30th to September 30th . Average S&P 500 Stock = S&P 500 Equal Weighted TR Index, Large Cap Value = Russell 1000 Value TR Index, Small Cap = Russell 2000 TR Index, Developed International = MSCI EAFE NR Index, S&P 500 = S&P 500 TR Index, Core Bonds = Bloomberg US Agg Bond TR Index, Large Cap Growth = Russell 1000 Growth TR Index.

    • Labor market data will be watched closely as investors look for information ahead of the Federal Reserve’s meetings in November and December.  
    William Winkeler
    About the Author

    Bill has more than 15 years of experience in the investment industry, most recently as Managing Director of Investments at a private wealth management firm. In his role at Confluence, Bill chairs the Investment Advisory Committee and develops and implements investment strategy for clients of the firm, as well as communicates investment content with clients.

  • ISOs vs. RSUs: Strategies to Optimize Your Employee Stock Benefits

    Employers are increasingly offering stock benefits as part of their compensation packages to remain competitive in the job market. These benefits often come in the form of Incentive Stock Options (ISOs) and Restrictive Stock Units (RSUs) which can be powerful tools for building wealth if managed effectively. However, understanding the differences in these benefits is crucial to maximizing their potential and avoiding costly mistakes.

    What Are ISOs and RSUs?

    Incentive Stock Options (ISOs) give the employee the option to purchase company stock at a fixed price, known as the exercise price. If the company’s stock price increases, you can buy shares at the lower exercise price and potentially sell them at the higher market price, resulting in a profit. The key advantage of ISOs is the potential for favorable tax treatment, where upon a qualifying sale, gains could be taxed at the lower long-term capital gains rate rather than as ordinary income.

    Restricted Stock Units (RSUs), on the other hand, are company shares granted to employees as part of their compensation. Unlike ISOs, RSUs are not options to buy stock; instead, they are actual shares that you receive usually after a certain vesting period. Once vested, RSUs are considered and taxed at their fair market value as ordinary income.

    Know Your Timeline: ISOs typically have a vesting schedule, meaning you can only exercise a portion of your options each year. Additionally, once you leave your company, you usually have a limited time to exercise your vested options.

    Understand the Tax Implications: ISOs offer a potential tax advantage, but they come with conditions. To qualify for long-term capital gains tax, you need to hold the shares for at least one year after exercising the option and two years after the grant date. Otherwise, your profits may be taxed as ordinary income.

    RSUs, while more straightforward than ISOs, still require strategic thinking:

    1. Plan for the Tax Hit: When your RSUs vest, they’re taxed as ordinary income. This means you might face a significant tax bill when your shares vest, even if you haven’t sold them yet. Some companies offer to withhold shares to cover taxes, but you’ll need to plan for any additional tax liability.  If you decide to hold on to the shares after vesting, you may be exposed to additional capital gains taxes if the stock appreciates and you sell at a later date.
    2. Consider Your Investment Strategy: Once your RSUs vest, you can choose to hold or sell the shares. Holding them can be a great way to participate in the company’s long-term success, but it also increases your exposure to the company’s stock. Balancing this with other investments in your portfolio is crucial to managing risk.
    3. Diversify Your Portfolio: It’s easy to get caught up in the success of your company, but putting too many eggs in one basket can be risky. Consider selling some of your vested RSUs to diversify your investments and reduce your exposure to company-specific risks.

    ISOs and RSUs are valuable components of a compensation package, offering the potential to build substantial wealth. However, understanding the details, planning for taxes, and integrating them into a broader financial strategy are essential steps to make the most of these benefits.

    At Confluence Financial Partners, we specialize in helping individuals navigate these complexities, ensuring that your stock benefits work in concert with your overall financial plan. If you have ISOs or RSUs and are unsure how to manage them, let’s have a conversation.

    Gregory Weimer
    About the Author

    Gregory developed a passion for the financial services industry early in life, drawn to the meaningful impact investing and thoughtful financial planning can have on people’s lives.

  • Building a Secure Retirement: The Confluence 401(k) Service Structure  

    Whether you are a business owner offering a retirement plan to your employees or are an employee participating in a company sponsored retirement plan, managing the benefit & saving for retirement both can feel like an isolating process. Too often we see a lack of guidance or knowledge from financial advisors to be able to serve as a resource to the company or its employees.  

    Confluence understands these challenges with a dedicated team of financial advisors collaborating with employee retirement plans. We have built a comprehensive 401(k) service structure – Confluence Standard of Care, designed to offer peace of mind to the employer, while supporting employees to make informed decisions to reach their financial & retirement goals. 

    Our 401(k) Standard of Care service structure centers on four key pillars: 

    1. Personalized Employer Review Meetings:  “One size fits all” does not work when it comes to 401(k) plans. Through regularly scheduled meetings, we collaborate with employers to monitor the employer plan to make sure it continues to fit the company’s needs and goals.  

    During these meetings we will discuss the following topics: 

    • Plan investment analysis: considering the quantitative and qualitative results to ensure we have skillful managers in place. 
    • Courageous plan design: striving to increase an employer’s benefits return on investment while striving to enhance participant retirement outcomes.  
    • Fee benchmarking: every 3 years we lead an RFP driven process to ensure apple-to-apple comparisons and to help maximize a plan’s negotiating leverage. 
    • Fiduciary guidance: to support the employer and mitigate potential liabilities. 

    2. Employee engagement:  Our education team uses highly customized plan participant content structured to help optimize outcomes and increase financial wellness. We deliver multiple types of meetings throughout the year. These meetings run the spectrum from group education to 1on1 individual consultations, and life stage education designed to meet the employee at their individual career stage.  

    3. Regular investment monitoring & investment analysis:  As a member of the Retirement Plan Advisor Group (RPAG), we have access to their proprietary fund ranking system that aims to enhance outcomes, manage risks, and reduce fiduciary exposure. Employers receive quarterly plan “report cards” detailing investments scores.  In addition to the fund scores, Confluence has an internal Investment Advisor Committee that provides guidance on selected investment managers and incorporates a qualitative layer of oversight to the fund analysis programs used.  

    4. Ongoing communication & support: In addition to the processes outlined above, we deliver a variety of additional touchpoints designed to keep employers and participants informed and engaged. This includes informative webinars, quarterly newsletters, and campaigns to address specific plan demographics or concerns.

    By utilizing these services, employers can have the confidence in knowing their 401(k) is managed effectively while employees have the opportunity to understand their benefits options.  

    Our team is here to guide you every step of the way. Should you have any questions or require further information on how our service delivery model can benefit your organization, please do not hesitate to contact us or listen to our podcasts today! 

    Confluence Wealth Services, LLC. d/b/a Confluence Financial Partners is a SEC-registered investment adviser. Confluence Financial Partners only transacts business in states where it is properly registered or notice filed or excluded or exempted from registration requirements. The security of electronic mail sent through the Internet is not guaranteed. All email sent to or from this address will be received or otherwise recorded by the Confluence Financial Partners corporate email system and is subject to archival, monitoring and/or review, by and/or disclosure to, someone other than the recipient. Confluence Financial Partners recommends you do not send confidential information to us via electronic mail, including social security numbers, account numbers, and personal identification numbers, unless properly encrypted. A copy of our current written disclosure statement discussing our advisory services and fees continues to remain available for your review upon request or by visiting the following link:https://www.confluencefp.com/form-adv-2a/

  • Stock Market Recap: July 2024

    • Major reversals across the equity market, with small cap stocks and value stocks outpacing the large-cap and growth peers sharply in July.
    • Catalyzed by decelerating inflation data, small cap stocks (Russell 2000 TR Index, +10.16%) finished significantly ahead of large cap stocks (S&P 500 TR Index, +1.22% and large cap growth stocks (Russell 1000 Growth TR Index, -1.70%).
    • Additionally, the S&P 500 had its first daily drop greater than 2% in July, the first time in over 350 trading days. This was the longest such streak of low daily volatility in over 15 years.

    Last month’s monthly update discussed the record levels of concentration in the S&P 500 – a factor that likely played a role in the significant shift equity markets saw in July.

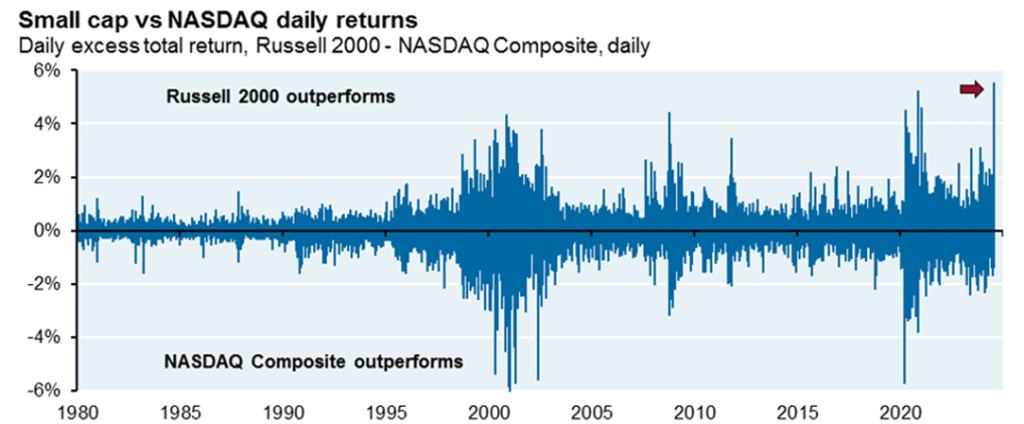
    After the June inflation (CPI) report was released, investors shifted expectations to a much higher likelihood of a rate cut in September. Generally, small cap stocks have a greater sensitivity to interest rates, given the use of more floating rate debt compared to large cap stocks. This factor, combined with improving earnings fundamentals, resulted in the Russell 2000 outperforming the NASDAQ by over 5% the day of the inflation report. This represents the largest single day outperformance of small cap stocks versus technology stocks in over 40-years (chart below)

    Source: JPMorgan Asset Management, Bloomberg, as of July 21, 2024

    Small caps kept up the momentum of July, along with large cap value stocks (Russell 1000 Value TR Index, +5.11%).

    July represented an important reminder to long-term investors about the benefits of maintaining a diversified approach

    • Earnings season wraps up in August: as of 7/29/2024, 40% of S&P 500 companies have reported earnings, and 76% are beating expectations for the second quarter.
    • The Federal Reserve is expected to use August to signal its intentions around cutting interest rates during its September meeting. The Federal Reserve last hiked in July 2023 and has held rates constant since.
    William Winkeler
    About the Author

    Bill has more than 15 years of experience in the investment industry, most recently as Managing Director of Investments at a private wealth management firm. In his role at Confluence, Bill chairs the Investment Advisory Committee and develops and implements investment strategy for clients of the firm, as well as communicates investment content with clients.